How to Sell My House With a Short Sale in Alabama
If you are searching for how to sell my house with a short sale in Alabama, there is a good chance you are already under some pressure. Maybe the mortgage balance is higher than what the house will sell for. Maybe payments have fallen behind. Maybe you are trying to avoid foreclosure and want to figure out whether a short sale is still possible. That is where understanding the process really matters.
A short sale is different from a normal home sale because the lender has to approve taking less than the full amount owed on the mortgage. That makes the process slower, more detailed, and usually more stressful than a standard sale. Still, for some homeowners in Alabama, it can be a real option when the house is underwater and keeping it is no longer realistic.
The most important thing to know is this. A short sale is not just about finding a buyer. It is about proving hardship, showing the lender the home cannot sell for enough to pay off the loan, and getting approval for the lender to accept less than what is owed.
What a Short Sale Means When You Need to Sell My House With a Short Sale in Alabama
A short sale happens when the sale price of the house is lower than the total mortgage payoff and the lender agrees to accept that reduced amount. In a normal sale, the mortgage gets paid in full at closing. In a short sale, the lender agrees to take a loss in order to avoid a worse outcome, like foreclosure.
That is why short sales take more work. The lender is not just signing off automatically. They are reviewing the property value, your hardship, your loan balance, your payment history, and the actual offer being made on the house.
For Alabama homeowners, this usually means there are multiple moving parts happening at once. You may be dealing with missed payments, foreclosure notices, financial pressure, and a lender that moves slower than you want them to. That is why many people start looking into both a short sale and a faster cash-sale option at the same time.
Why Homeowners Search How to Sell My House With a Short Sale in Alabama
Most homeowners do not look into a short sale unless something has already gone wrong financially. In many cases, the house is worth less than what is owed because of market changes, a refinance done at the wrong time, missed payments, fees added to the balance, or a property that needs more work than the owner can afford.
Common reasons people start looking at how to sell my house with a short sale in Alabama include:
- behind on mortgage payments
- job loss or reduced income
- divorce
- medical bills
- relocation
- house value dropped below loan balance
- major repair issues
- inherited a property with debt
- trying to avoid foreclosure
- unable to afford two homes
A short sale can sometimes help avoid a full foreclosure, but it is not always the fastest or easiest answer. That is why it helps to compare it against other selling options early.
How to Start the Process to Sell My House With a Short Sale in Alabama
The first step is figuring out whether a short sale is even necessary. That means confirming how much is owed on the mortgage, what fees or arrears have built up, and what the property is likely worth in its current condition. If the house can sell for enough to cover the loan, then it may not need a short sale at all.
If the numbers show you are underwater, the next step is usually contacting the lender and asking about their short sale process. Each lender has its own package and requirements, but most want financial documents, hardship information, and details about the property. Many homeowners also work with a real estate professional, attorney, or investor who understands distressed property situations.
At the same time, it can help to review related resources like Stop Foreclosure Alabama, Can You Sell a House in Foreclosure Alabama?, and Questions About Selling My House because short sale situations often overlap with foreclosure concerns.
How Lender Approval Affects Sell My House With a Short Sale in Alabama
This is the part that makes short sales harder than regular home sales. Even if you find a buyer, the sale is not done until the lender approves it. The lender will usually look at the offer, compare it to what they think the property is worth, and decide whether accepting that offer makes more sense than pushing the property toward foreclosure.
That means the timeline is often unpredictable. Some lenders move faster than others. Some ask for more paperwork. Some counter the offer. Some reject the short sale entirely if they think the house should bring more money.
For homeowners under real time pressure, this can be frustrating. You may have a buyer ready, but you are still waiting on the bank. That is why some Alabama sellers also explore direct cash-buyer options while pursuing lender conversations, just in case the short sale drags out too long.
Documents You May Need to Sell My House With a Short Sale in Alabama
Most short sale lenders ask for a fairly complete hardship package. While requirements vary, homeowners are often asked to provide financial statements, pay stubs or proof of income, tax returns, bank statements, a hardship letter, and authorization forms. The lender may also request repair details, property photos, or market information showing the home is not worth enough to cover the debt.
The hardship letter matters because it explains why the homeowner can no longer keep making payments and why the short sale makes sense. It should be honest and clear. The lender is trying to understand why taking less than the balance is justified.
This is one reason short sales can feel overwhelming. They are not just real estate transactions. They are financial review processes too.
Sell My House With a Short Sale in Alabama vs Foreclosure
A lot of homeowners compare these two because they are trying to avoid the worst-case outcome. A short sale is usually seen as the more controlled option because you are actively trying to sell the home instead of letting the foreclosure process fully play out.
That said, a short sale still takes time, and time is exactly what some homeowners do not have. If foreclosure deadlines are close, waiting on lender approval may not feel safe enough. In that case, it may be worth looking at alternatives that can move faster.
Green South House Buyers has related pages that connect naturally to this topic, including Sell My Foreclosure House, Stop Foreclosure Alabama, and Can You Sell a House in Foreclosure Alabama?. Those pages fit well because many homeowners looking into short sales are really trying to prevent foreclosure from going further.
How Condition of the Property Affects Sell My House With a Short Sale in Alabama
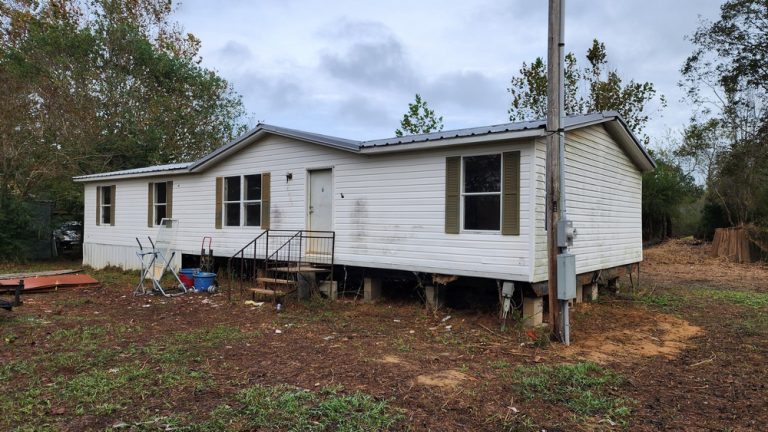
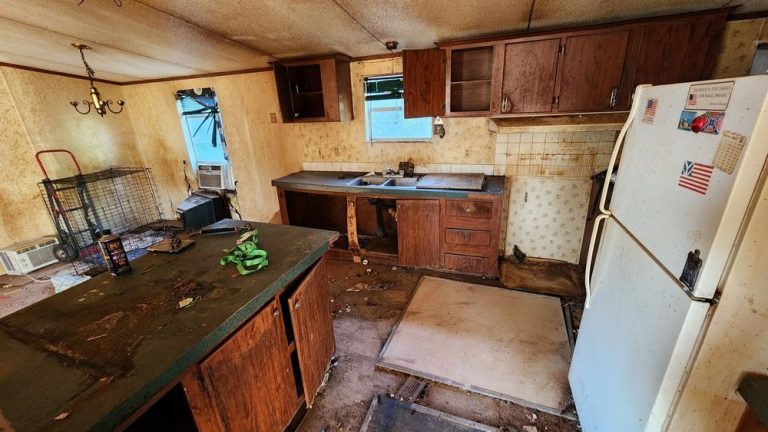
The condition of the house matters more than many sellers expect. If the home needs heavy repairs, it may be harder to attract a traditional buyer willing to wait through the short sale process. Buyers already know short sales can take time, so if the house also needs a roof, HVAC work, flooring, plumbing, or major updates, the pool of interested buyers gets even smaller.
That is why some underwater homeowners start looking at both short sale options and as-is selling options. If the property needs work and the lender is slow, it may be harder to hold everything together long enough for a traditional buyer to stay committed.
Pages like How To Sell a House AS IS in Alabama and We Buy Foreclosed Houses are helpful internal links here because they speak to the type of seller who is also dealing with condition issues and time pressure.
Can a Cash Buyer Help If I Need to Sell My House With a Short Sale in Alabama
Yes, sometimes. A cash buyer does not automatically remove the lender approval requirement in a short sale, but it can simplify the buyer side of the deal. There is no bank financing on the buyer’s end, which can reduce some of the delay and uncertainty.
That matters because a financed buyer may get tired of waiting for the lender’s short sale approval. A cash buyer may be more patient, more familiar with distressed property situations, and more open to buying the house as-is. That can make the overall deal easier to hold together.
Green South House Buyers positions itself around fast cash offers, as-is purchases, and foreclosure-related situations, which makes pages like How We Buy Houses, Get Cash Offer, and Contact Us useful internal links for this topic.
Mistakes to Avoid When Trying to Sell My House With a Short Sale in Alabama
One big mistake is waiting too long to ask what the lender will require. Many homeowners lose time because they assume the process will be simpler than it is. The earlier you understand the numbers and the paperwork, the better.
Another mistake is listing the property without being realistic about timeline and price. If the house is overpriced, it may sit too long. If the foreclosure timeline is already tight, that lost time matters.
A third mistake is focusing only on the short sale without comparing other options. A short sale can work, but it is not always the best answer for every seller. If speed, certainty, or heavy repairs are part of the picture, a direct sale may deserve just as much attention.
Best Next Steps for How to Sell My House With a Short Sale in Alabama
If you are serious about how to sell my house with a short sale in Alabama, start with the numbers. Confirm what you owe, what the house is likely worth, and whether a normal sale is even possible. Then contact the lender and learn what their short sale process looks like.
After that, compare your realistic options. If the lender seems open, the timeline still works, and the property can attract a buyer, a short sale may be worth pursuing. If the house needs work, deadlines are tight, or the process feels too uncertain, then looking at an as-is cash buyer may be the smarter route.
Useful internal pages to support this topic include Stop Foreclosure Alabama, Can You Sell a House in Foreclosure Alabama?, How To Sell a House AS IS in Alabama, Questions About Selling My House, and Contact Us.
Need Help Figuring Out How to Sell My House With a Short Sale in Alabama
A short sale can be a path forward, but it is not a simple sale. It takes lender approval, paperwork, patience, and a real understanding of your timeline. For some Alabama homeowners, it is the right move. For others, the better solution is a faster direct sale before the situation gets worse.
If you are trying to sort through how to sell my house with a short sale in Alabama, the most important thing is not to stay stuck. Get clear on the numbers, understand the lender process, and compare that path against your other selling options. That way, you can make a decision based on what actually works for your house, your timeline, and your situation.